Chartered Accountancy & Tax Knowledge Blog
In-depth technical articles authored by our partners and research wing, providing practical clarity on statutory thresholds, GST input reconciliations, and corporate internal financial controls.
Section 43B(h) MSME 45-Day Payment Rule: Tax Disallowance, Due Dates & Compliance
Section 43B(h) of the Income-tax Act, 1961 has significant implications for businesses that delay payments to Micro and Small Enterprises (MSEs). Where an amount payable to an eligible MSE is not paid within the time prescribed under Section 15 of the MSMED Act, 2006, the expenditure may be disallowed for income-tax purposes for that year. The provision applies from Assessment Year 2024–25 onwards and is particularly important during year-end tax and audit proceedings. Unlike several other provisions covered under Section 43B, the benefit of payment up to the income-tax return filing due date is not available for clause (h). Businesses therefore need to identify qualifying MSE suppliers, determine the applicable payment period and assess outstanding balances before finalising their accounts.
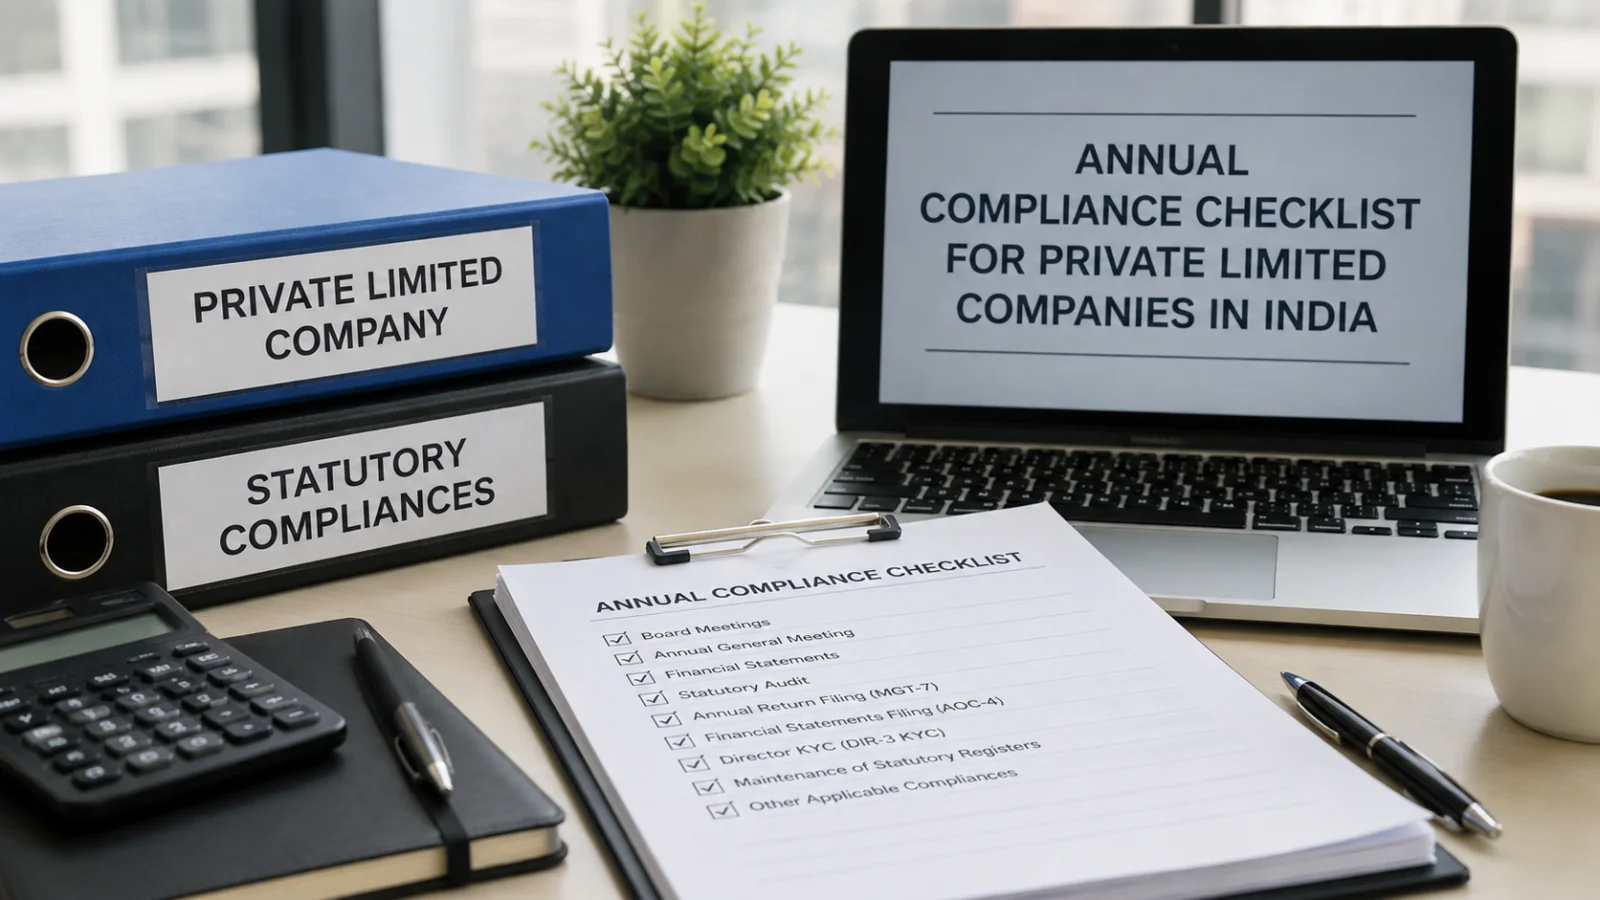
Annual Compliance Checklist for Private Limited Companies in India
A Private Limited Company in India is subject to a range of recurring compliance requirements under the Companies Act, 2013. These obligations continue even when the company has limited business activity or no significant transactions during the year. Annual compliance generally covers financial statements, annual return, Board meetings, Annual General Meeting (AGM), statutory audit and filings with the Registrar of Companies (ROC). Depending on the company's activities and circumstances, additional compliances relating to directors, auditors, related-party transactions, deposits, loans, charges and other corporate matters may also apply. For companies, timely compliance is important not only to avoid additional fees and penalties but also to maintain a clean corporate record and prevent difficulties in future transactions such as fundraising, bank financing, mergers, investments or closure of the company.
GST Annual Return GSTR-9: Reconciliation, Common Errors, Amendments & Year-End Compliance
Form GSTR-9 is the annual return prescribed under the GST law for eligible registered taxpayers. It consolidates the details of outward supplies, inward supplies, input tax credit, tax paid, refunds, demands and other relevant information reported during the financial year. GSTR-9 is not merely a compilation of previously filed GST returns. It provides an important year-end reconciliation exercise between the figures reported in GSTR-1, GSTR-3B, books of account and other relevant GST records. For financial years from FY 2024-25 onwards, registered persons having aggregate turnover of up to ₹2 crore in the relevant financial year are exempt from filing the annual return, pursuant to Notification No. 15/2025–Central Tax. For taxpayers required to file GSTR-9, careful reconciliation is essential because differences in turnover, tax liability, input tax credit and amendments can result in additional tax exposure or reporting inconsistencies.
Stay Informed with Regulatory & Tax Circulars
Receive concise, partner-vetted summaries of CBDT notifications, GST amendments, and MCA compliance due dates directly to your inbox.